The UAE Financial Vocabulary: Making Sense of the Terms You See Every Day
Walk into any UAE bank, browse a credit-card comparison page or scroll through an offer online, and you are likely to come across a familiar pattern. One card promises attractive cashback, another highlights airport benefits and travel rewards, while another focuses on dining, entertainment or lifestyle privileges. At first glance, comparing them seems simple. Then you start reading the details and encounter terms such as credit limit, available credit, outstanding balance, annual fee, minimum payment, APR, profit rate and eligibility.
For customers exploring Islamic financial products, the terminology can become even broader, with terms such as Murabaha, Tawarruq and Shari'ah-compliant appearing in product information.
None of these terms are necessarily difficult on their own. The challenge is understanding what they mean when you are deciding how to use a credit card or comparing one card with another. Financial terminology can often feel disconnected from everyday spending, which makes it easy to focus on the headline offer without fully understanding the product behind it.
The good news is that you do not need to become a financial expert to make sense of credit-card terminology. Understanding a few of the most used terms can make it much easier to read an offer, understand your statement and decide whether a particular card fits your spending habits.
Here is how some of the most important terms translate into real-life situations.
How Much Can You Actually Spend?
One of the first things you may notice when using a credit card is your credit limit. This is the maximum amount you can use on the card, subject to the terms and conditions set by the issuing bank. For example, imagine that your card has a credit limit of AED 20,000.
You use the card to pay AED 1,000 for groceries, AED 800 for dining and AED 1,200 for other expenses. You have now used AED 3,000 of your available limit. Your original credit limit remains AED 20,000, but the amount you can currently use has changed.
This is where the term available credit becomes relevant. Available credit refers to the amount that remains available for you to use at a particular point in time. In this example, assuming there are no other transactions or adjustments, you would have approximately AED 17,000 available.
You may also see the term outstanding balance on your account or statement. This generally refers to the amount currently owed on the card based on transactions and account activity. The outstanding balance can change as you make new purchases or payments.
Understanding the difference between these three terms gives you a clearer picture of your card. The credit limit tells you the maximum amount available, available credit tells you how much of that limit remains to use, and the outstanding balance tells you what you currently owe.
How Much Do You Need to Pay?
Credit-card statements can introduce another set of terms that may initially seem confusing. You may see a statement date, payment due date, minimum payment and total amount due, sometimes all appearing close together
The statement date is the date on which your billing cycle is recorded and your statement is generated. It provides a snapshot of the transactions and amounts associated with that billing period.
The payment due date is the date by which the required payment needs to be made according to the card's terms. Keeping track of this date is an important part of managing a credit card because it tells you when your payment is expected.
Then there is the total amount due, which represents the amount shown as payable on your statement, and the minimum payment, which is the minimum amount you are required to pay by the due date, subject to the product's terms.
These figures can be confusing when you first encounter them because they can be very different. For example, your statement could show a total amount due of AED 2,500 while the minimum payment may be AED 125. Both figures appear on the same statement, but they serve different purposes.
Rather than looking at the smallest number and assuming it represents the full cost of your spending, it is important to understand what each figure means and how your card's payment terms work. Reading your statement carefully can make managing your card much more straightforward.
Interest Rate, Profit Rate and Why the Language Changes
If you have compared different financial products in the UAE, you may have noticed that not every bank uses the same terminology. This is partly because the UAE has both conventional and Islamic banking products, which can use different terms and structures.
Conventional financial products commonly use terms such as interest rate and APR, while Islamic financial products may refer to a profit rate and describe the product as Shari'ah-compliant.
You may also encounter the term Murabaha when exploring Islamic financial products. In simple terms, Murabaha is an Islamic finance structure involving a disclosed cost and an agreed profit margin as part of a transaction. The exact application and structure depend on the financial product, which is why the product's own documentation remains the best source for understanding how a particular card or facility works.
Another term you may come across is Tawarruq, which is another structure used in Islamic finance.
The important point for consumers is not to memorise every term associated with Islamic finance. Instead, when you come across terminology that is unfamiliar, understand how it applies to the product you are considering.
The language may differ between conventional and Islamic products, but the principle of making an informed decision remains the same: understand the terms, consider the costs and benefits, and choose based on what suits your circumstances.
What Does APR Actually Tell You?
APR, or Annual Percentage Rate, is another term that frequently appears when discussing credit. In simple terms, it provides an annualised way of expressing the cost of credit and can help consumers understand and compare the cost associated with relevant credit products.
However, APR is not the only number worth considering when looking at a credit card.
Credit cards are often designed around a combination of features. A card might offer cashback, travel benefits, dining rewards, lifestyle privileges or other features alongside its applicable costs and terms. Two cards can therefore look very different even if they appear to offer similar headline benefits.
This is why looking at one number in isolation can leave out important parts of the picture. The more useful approach is to consider the overall product, including its costs, benefits, eligibility requirements and payment terms.
Understanding APR is useful but understanding how the entire card works is even more important.
An Annual Fee Doesn't Tell You the Whole Story
The words annual fee can immediately make a credit card seem more expensive. But an annual fee, by itself, does not tell you whether a card offers good value for a particular customer.
Consider two people with completely different spending habits. One person may frequently travel, regularly use airport-related benefits and spend heavily in categories where a particular card offers rewards. Another person may rarely travel and mainly use a credit card for everyday purchases
The same card can therefore have very different value for these two customers
This is why the better question is not simply, “Does this card have an annual fee?” It is, “What am I getting from this card, and is it relevant to the way I spend?”
A card may have an annual fee while offering benefits that are useful to a particular customer. Another card may have a different fee structure and a different combination of rewards.
When comparing cards, it makes sense to look at the overall proposition rather than judging a product based on a single cost or benefit. The value of a card ultimately depends on how well its features fit the person using it.
Cashback Doesn't Always Mean the Same Thing
Cashback is one of the most visible benefits in credit-card marketing, and it is easy to understand why. Seeing a headline such as “up to 5% cashback” immediately gives you a sense of what the card is trying to offer.
But the phrase “up to” matters.
A cashback rate may apply to spending categories rather than every purchase made with the card. There may also be monthly or annual limits, minimum spending requirements, eligible transaction categories or other conditions.
Imagine that you regularly spend on groceries, dining and fuel. A card offering a high cashback rate may appear attractive, but what matters is whether those categories qualify, how much cashback you can earn and whether any limits apply.
This is why comparing cashback cards is about more than comparing percentages. The highest advertised rate is not automatically the most useful option.
Instead, look at how the cashback programme works and ask whether it matches your actual spending habits. A slightly different reward structure could potentially be more relevant if it aligns more closely with where you spend your money.
Eligibility: Why Can't Everyone Get the Same Card?
Another term that appears frequently in credit-card offers is eligibility.
Seeing a card advertised online does not automatically mean that every customer will qualify for it. Different cards are designed for different customer segments and may have their own eligibility criteria, which can include factors such as income, employment details, residency and other requirements determined by the issuing bank.
This is important because two people can look at the same credit-card offer and have different options available to them.
Eligibility is therefore worth considering early in the comparison process. There is little value in focusing entirely on a card's rewards and benefits if you have not first established whether you meet the applicable requirements.
At the same time, eligibility should not be confused with the value of the card itself. A card can be a strong fit for one customer and not be suitable or available for another. The objective is to understand which options are relevant to you and then compare them based on what they offer.
The UAE Has More Than One Banking Language
Part of the financial vocabulary gap comes from the variety of banking products available in the UAE.
When exploring conventional products, you are likely to encounter terminology such as interest, APR, credit limit, annual fee and minimum payment. When exploring Islamic products, you may encounter terms such as profit rate, Shari'ah-compliant, Murabaha and Tawarruq.
For someone who is simply trying to choose a credit card, this can feel like two different financial languages.
But you do not need to know every technical definition before you can compare your options. What matters is understanding the terminology relevant to the product you are considering and knowing where to find the specific terms, conditions, charges and benefits that apply.
The UAE's banking landscape gives consumers access to different types of financial products. Understanding the language used to describe those products makes it easier to explore that choice with confidence.
So, What Should You Actually Look At?
Once you move beyond the terminology, comparing a credit card can become much simpler. Instead of trying to remember a long list of financial definitions, focus on five practical areas
First, consider eligibility. Check whether you meet the requirements for the card before spending time comparing its features in detail.
Second, look at cost. Understand any applicable annual fees, charges and other costs associated with the product. Knowing what a card costs helps you evaluate its overall value.
Third, consider the benefits. Look beyond the headline offer and understand what the card provides, whether that is cashback, travel benefits, dining rewards, lifestyle privileges or other features.
Fourth, think about usage. A reward is only useful if it fits the way you spend. If you rarely travel, for example, travel-focused benefits may not be as relevant to you as everyday cashback or lifestyle rewards.
Finally, understand the payment terms. Know your statement date, payment due date, minimum payment and total amount due, and make sure you understand the terms that apply to your balance.
These five areas can help turn a complicated-looking credit-card comparison into a much more practical decision.
Understanding Your Choices Comes First
Financial terminology should not make choosing a credit card feel more complicated than it needs to be. Once you understand the basics, you can look beyond the headline offer and start comparing what matters to you, whether that is cashback, travel benefits, lifestyle rewards, fees, eligibility or payment terms.
This is where TestMyCard can make exploring your options simpler.
TestMyCard brings together credit-card options available in the UAE, including conventional and Islamic options, so you can explore different products in one place. Rather than getting lost in unfamiliar financial terminology or focusing only on a single headline benefit, you can look at the features and options that are relevant to what you are looking for.
Because the right credit card is not necessarily the one with the biggest number in its advertisement. It is the one whose features, benefits, costs and terms make sense for you.
Latest Post
Choosing the Right Credit Card for Your Family in the UAE
Family life in the UAE comes with a unique spending pattern. Unlike single professionals who may concentrate their expenses on travel, dining, or lifestyle purchases,
How Much Credit Card Cashback Can You Realistically Earn in a Year
One of the most common questions credit card users in the UAE ask is simple, but important
The Smart Traveller's Guide to Using Credit Cards Abroad
For many UAE residents, international travel is no longer a once-a-year event. Whether it is a summer escape to Europe, a family holiday in Asia, or a quick city break over a long weekend, spending abroad has become a regular part of life.
Best Credit Cards for Booking Flights and Hotels This Summer in the UAE
Summer is one of the busiest travel seasons for UAE residents. Whether you're heading to London for cooler weather, Istanbul for a long weekend, the Maldives for a family holiday, or flying home to visit relatives, chances are your biggest expenses will be flights and accommodation.
How to Maximise Credit Card Rewards Without Overspending in the UAE
Most people in the UAE approach credit card rewards the wrong way. They assume more spending means more rewards
Premium vs. Entry-Level Credit Cards in the UAE- Is the Annual Fee Worth It?
You have seen them, the sleek metal cards, the platinum tiers, the promises of lounge access and complimentary chauffeur rides
How to Maximise Your Credit Card Rewards This Eid Al-Adha
Eid Al-Adha is almost here, falling on 26th May this year, and with it comes one of the biggest spending seasons on the UAE calendar
Should You Get Multiple Credit Cards? A UAE Guide
If you've ever wondered whether having more than one credit card is a smart move or a recipe for debt
Best Credit Cards for Dining in the UAE : Earn While You Eat
Let's be honest — if your credit card isn't rewarding your Friday brunch, your weeknight takeaway, or your third coffee of the day, it's not working harder for you.
The Best Credit Cards for Grocery Shopping in the UAE
Groceries are non-negotiable. For a typical UAE household of four, monthly supermarket spending ranges from AED 2,500 to AED 4,000
How to Apply for Your First Credit Card in the UAE
Applying for a Credit Card in the UAE should be simple. Between salary thresholds, AECB score requirements, and a market that has genuinely changed in 2025,
Cashback vs. Air Miles: Which UAE Credit Card Is Right for You?
Credit cards in the UAE offer an impressive array of benefits. Two of the most popular features residents look for are cashback rewards and air miles. Each offers distinct advantages, but they work differently and suit different spending habits.
5 Common Mistakes to Avoid When Choosing a Credit Card in the UAE
Credit cards in the UAE offer a world of convenience and valuable benefits — from cashback and travel rewards to shopping discounts and exclusive services. Yet, despite countless offers and promotions, many residents end up choosing cards that don’t truly suit their needs.
How to Use Test My Card to Find the Best Credit Card for You in Minutes
The UAE has one of the most diverse credit card markets in the world. Cashback, air miles, shopping discounts, travel perks—every bank offers different deals to attract customers. While this competition benefits consumers, it also creates confusion.
Salary Below AED 5,000 in the UAE? What You Should Know About Credit Card Eligibility
In the UAE, many residents earning below AED 5,000 assume that credit cards are completely out of reach. While income requirements do play an important role, it is equally essential to understand how today’s lending rules
Top 5 Credit Cards in the UAE with No Annual Fees
For many residents in the UAE, credit cards are essential tools for everyday life — offering convenience, security, and valuable rewards. However, one feature that often frustrates users is the annual fee
The UAE Financial Vocabulary: Making Sense of the Terms You See Every Day
Walk into any UAE bank, browse a credit-card comparison page or scroll through an offer online, and you are likely to come across a familiar pattern.

The Convenience of “Buy Now”: How Delayed Payments Change the Way We Spend
You see a phone priced at AED 3,000. Then, right next to it, you see: AED 250 per month.
The Financial Domino Effect: How One Money Decision Can Change Everything Else
Money decisions rarely happen in isolation. You may think you are simply taking a new credit card, increasing your credit limit, moving to a more expensive apartment, taking a personal loan, or switching your bank.
The Spending Paradox: Why a High Salary Can Still Feel Like It's Not Enough
A higher salary should make you feel financially better off. You earn more, so naturally, you expect to have more money available for savings, investments, travel and the things you enjoy
Financial FOMO: Are You Choosing Products Because Everyone Else Is?
Your colleague just got a new credit card because the cashback is insane. Your cousin switched banks because their favourite influencer swears by it.
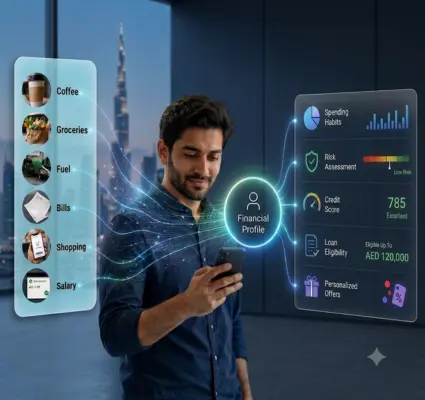
The Data Behind Your Wallet: How Banks Understand Your Financial Behaviour
Every time you tap your card at a coffee shop, pay a utility bill, or transfer money to a friend, you're leaving behind a small piece of information.
Your Money Personality: Are You a Saver, Spender, Optimiser, or Maximiser?
Ask two people with the same salary how they handle money, and you'll often get two completely different answers. One keeps a strict budget and rarely touches their savings.
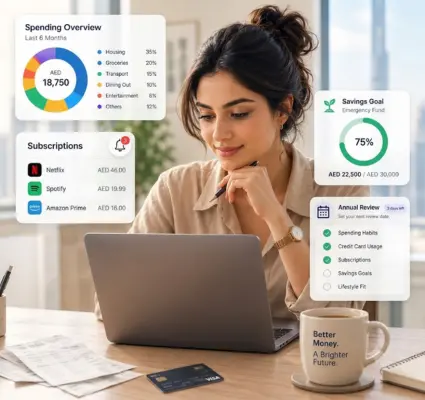
The Personal Finance Reset: 5 Things Everyone Should Review Every Year
Most of us wouldn't drive a car for a full year without a service check. Yet many people go twelve months or more without giving their finances the same basic maintenance
How AI Is Changing the Way UAE Residents Choose Credit Cards
Until recently, choosing a credit card in the UAE meant scrolling through bank websites, opening a handful of tabs
Big-Ticket Purchases Made Easy: How 0% Instalment Plans Work on UAE Credit Cards
Buying a new laptop, upgrading your home appliances, or booking a family trip often means spending a large amount of money in one go. For many UAE residents
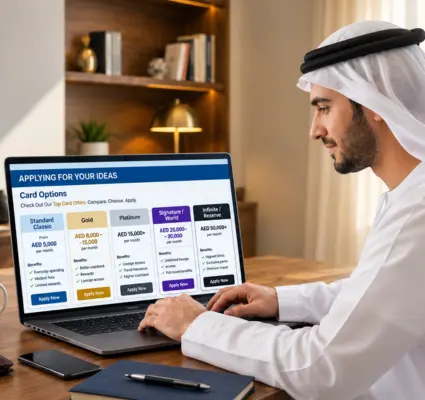
How Minimum Salary Thresholds Are Set and Why They Vary by Card Tier
Every UAE bank checks one thing first when reviewing a credit card application: your monthly salary. Before anything else is considered
The Rise of Super App Co-Branded Cards (noon, Talabat, Careem) and What They Mean for Your Rewards
UAE banks are increasingly building credit cards around the apps people already use every day, rather than offering generic cashback on broad spending categories
Understanding Interest-Free Periods : How to Enjoy Your Credit Card Without Paying a Dirham in Interest
Picture this: your salary gets credited on the 1st, and by the 25th, you've swiped your card for everything from groceries to a weekend trip.
The Psychology of Swiping: Why Credit Cards Feel Different from Cash
Picture two Fridays. On the first, you withdraw AED 500 in cash for brunch at a restaurant in Dubai Marina, and you feel every dirham leave your wallet as the bill adds up.
How to Build a Strong Credit History in the UAE Using Your Credit Card
Most people in the UAE get a credit card for the rewards. The cashback, the lounge access, and the dining discounts are the obvious reasons.
Why 2026 Is the Best Time to Be a Credit Card Holder in the UAE
Credit cards in the UAE have historically been approached with a degree of caution. While the rewards on offer were often appealing, eligibility requirements, complex fee structures
Choosing the Right Credit Card for Your Family in the UAE
Family life in the UAE comes with a unique spending pattern. Unlike single professionals who may concentrate their expenses on travel, dining, or lifestyle purchases,
How Much Credit Card Cashback Can You Realistically Earn in a Year
One of the most common questions credit card users in the UAE ask is simple, but important
The Smart Traveller's Guide to Using Credit Cards Abroad
For many UAE residents, international travel is no longer a once-a-year event. Whether it is a summer escape to Europe, a family holiday in Asia, or a quick city break over a long weekend, spending abroad has become a regular part of life.
Best Credit Cards for Booking Flights and Hotels This Summer in the UAE
Summer is one of the busiest travel seasons for UAE residents. Whether you're heading to London for cooler weather, Istanbul for a long weekend, the Maldives for a family holiday, or flying home to visit relatives, chances are your biggest expenses will be flights and accommodation.
How to Maximise Credit Card Rewards Without Overspending in the UAE
Most people in the UAE approach credit card rewards the wrong way. They assume more spending means more rewards
Premium vs. Entry-Level Credit Cards in the UAE- Is the Annual Fee Worth It?
You have seen them, the sleek metal cards, the platinum tiers, the promises of lounge access and complimentary chauffeur rides
How to Maximise Your Credit Card Rewards This Eid Al-Adha
Eid Al-Adha is almost here, falling on 26th May this year, and with it comes one of the biggest spending seasons on the UAE calendar
Should You Get Multiple Credit Cards? A UAE Guide
If you've ever wondered whether having more than one credit card is a smart move or a recipe for debt
Best Credit Cards for Dining in the UAE : Earn While You Eat
Let's be honest — if your credit card isn't rewarding your Friday brunch, your weeknight takeaway, or your third coffee of the day, it's not working harder for you.
The Best Credit Cards for Grocery Shopping in the UAE
Groceries are non-negotiable. For a typical UAE household of four, monthly supermarket spending ranges from AED 2,500 to AED 4,000
How to Apply for Your First Credit Card in the UAE
Applying for a Credit Card in the UAE should be simple. Between salary thresholds, AECB score requirements, and a market that has genuinely changed in 2025,
Cashback vs. Air Miles: Which UAE Credit Card Is Right for You?
Credit cards in the UAE offer an impressive array of benefits. Two of the most popular features residents look for are cashback rewards and air miles. Each offers distinct advantages, but they work differently and suit different spending habits.
5 Common Mistakes to Avoid When Choosing a Credit Card in the UAE
Credit cards in the UAE offer a world of convenience and valuable benefits — from cashback and travel rewards to shopping discounts and exclusive services. Yet, despite countless offers and promotions, many residents end up choosing cards that don’t truly suit their needs.
How to Use Test My Card to Find the Best Credit Card for You in Minutes
The UAE has one of the most diverse credit card markets in the world. Cashback, air miles, shopping discounts, travel perks—every bank offers different deals to attract customers. While this competition benefits consumers, it also creates confusion.
Salary Below AED 5,000 in the UAE? What You Should Know About Credit Card Eligibility
In the UAE, many residents earning below AED 5,000 assume that credit cards are completely out of reach. While income requirements do play an important role, it is equally essential to understand how today’s lending rules
Top 5 Credit Cards in the UAE with No Annual Fees
For many residents in the UAE, credit cards are essential tools for everyday life — offering convenience, security, and valuable rewards. However, one feature that often frustrates users is the annual fee
The UAE Financial Vocabulary: Making Sense of the Terms You See Every Day
Walk into any UAE bank, browse a credit-card comparison page or scroll through an offer online, and you are likely to come across a familiar pattern.
The Convenience of “Buy Now”: How Delayed Payments Change the Way We Spend
You see a phone priced at AED 3,000. Then, right next to it, you see: AED 250 per month.
The Financial Domino Effect: How One Money Decision Can Change Everything Else
Money decisions rarely happen in isolation. You may think you are simply taking a new credit card, increasing your credit limit, moving to a more expensive apartment, taking a personal loan, or switching your bank.
The Spending Paradox: Why a High Salary Can Still Feel Like It's Not Enough
A higher salary should make you feel financially better off. You earn more, so naturally, you expect to have more money available for savings, investments, travel and the things you enjoy
Financial FOMO: Are You Choosing Products Because Everyone Else Is?
Your colleague just got a new credit card because the cashback is insane. Your cousin switched banks because their favourite influencer swears by it.
The Data Behind Your Wallet: How Banks Understand Your Financial Behaviour
Every time you tap your card at a coffee shop, pay a utility bill, or transfer money to a friend, you're leaving behind a small piece of information.
Your Money Personality: Are You a Saver, Spender, Optimiser, or Maximiser?
Ask two people with the same salary how they handle money, and you'll often get two completely different answers. One keeps a strict budget and rarely touches their savings.
The Personal Finance Reset: 5 Things Everyone Should Review Every Year
Most of us wouldn't drive a car for a full year without a service check. Yet many people go twelve months or more without giving their finances the same basic maintenance
How AI Is Changing the Way UAE Residents Choose Credit Cards
Until recently, choosing a credit card in the UAE meant scrolling through bank websites, opening a handful of tabs
Big-Ticket Purchases Made Easy: How 0% Instalment Plans Work on UAE Credit Cards
Buying a new laptop, upgrading your home appliances, or booking a family trip often means spending a large amount of money in one go. For many UAE residents
How Minimum Salary Thresholds Are Set and Why They Vary by Card Tier
Every UAE bank checks one thing first when reviewing a credit card application: your monthly salary. Before anything else is considered
The Rise of Super App Co-Branded Cards (noon, Talabat, Careem) and What They Mean for Your Rewards
UAE banks are increasingly building credit cards around the apps people already use every day, rather than offering generic cashback on broad spending categories
Understanding Interest-Free Periods : How to Enjoy Your Credit Card Without Paying a Dirham in Interest
Picture this: your salary gets credited on the 1st, and by the 25th, you've swiped your card for everything from groceries to a weekend trip.
The Psychology of Swiping: Why Credit Cards Feel Different from Cash
Picture two Fridays. On the first, you withdraw AED 500 in cash for brunch at a restaurant in Dubai Marina, and you feel every dirham leave your wallet as the bill adds up.
How to Build a Strong Credit History in the UAE Using Your Credit Card
Most people in the UAE get a credit card for the rewards. The cashback, the lounge access, and the dining discounts are the obvious reasons.
Why 2026 Is the Best Time to Be a Credit Card Holder in the UAE
Credit cards in the UAE have historically been approached with a degree of caution. While the rewards on offer were often appealing, eligibility requirements, complex fee structures

