How to Choose the Right Credit Card for Online Shopping in the UAE
Online shopping has become a regular part of life in the UAE. From ordering groceries and electronics to buying clothes, booking services and shopping during major sales, digital payments make everyday purchases easier.
Many credit cards offer cashback, reward points, discounts, and other benefits on online transactions. However, not every card offers the same value, and some benefits come with spending conditions, monthly limits, or exclusions.
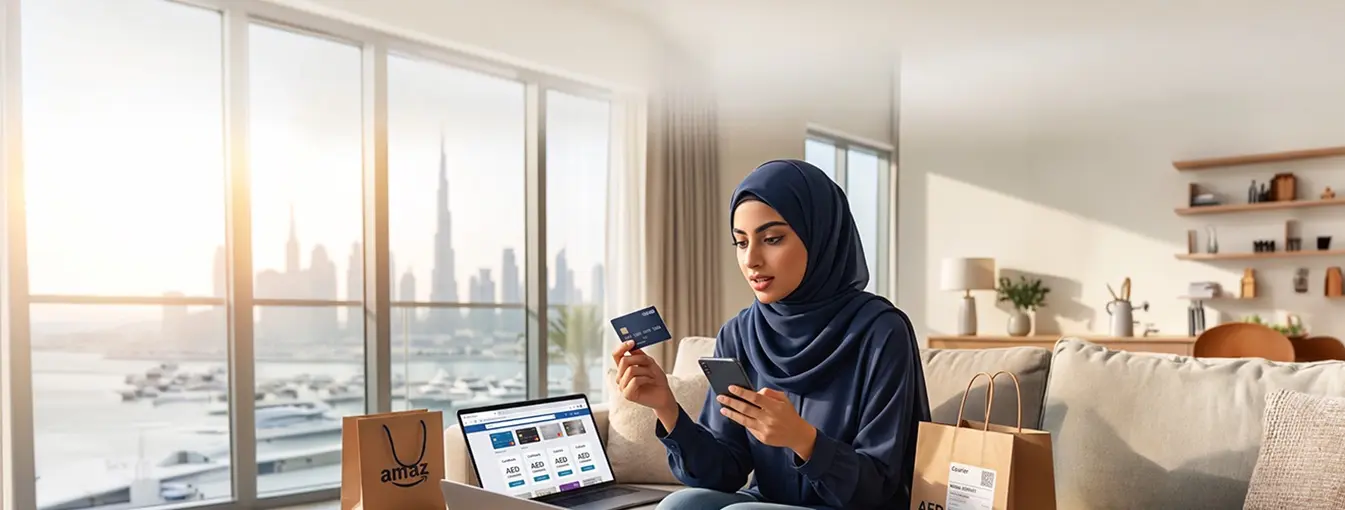
Choosing the right credit card for online shopping is not just about finding the highest advertised cashback rate. It is about understanding your spending habits, comparing the actual benefits, and selecting a card that suits your needs.
Here is what UAE residents should consider before choosing a credit card for online purchases.
Understand Your Online Shopping Habits
Before comparing credit cards, start by understanding where and how you spend your money.
Some people regularly order groceries and household essentials online. Others spend more on fashion, electronics, food delivery, travel bookings, or subscriptions.
Your spending pattern can help determine which card benefits are most useful.
For example, if you frequently order groceries, a card offering rewards on supermarket purchases may be more suitable than one focused on travel benefits. If you shop across several online platforms, a card with broader rewards on eligible retail spending may offer greater flexibility.
Review your recent transactions and identify your most common spending categories.
You do not need to change your shopping habits to earn rewards. Instead, choose a card that rewards the purchases you already make.
Compare Cashback and Reward Points
Cashback and reward points are two common benefits offered by UAE credit cards. Both can provide value, but they work differently.
Cashback Credit Cards
Cashback cards return a percentage of eligible spending as cashback or a similar monetary benefit, depending on the card's terms.
For example, if a card offers two per cent cashback on eligible online purchases and you spend AED 1,000, you could earn AED 20 before considering any applicable caps, exclusions or conditions.
However, the advertised rate may not apply to every transaction. Some cards offer higher cashback only on selected categories, while others require a minimum monthly spend.
Reward Points Credit Cards
Reward points can be redeemed for eligible benefits such as shopping vouchers, travel bookings, or other rewards, depending on the program.
Their value varies between programs and redemption options. Before choosing a rewards card, check how points are earned, whether they expire, and how they can be redeemed.
The best option depends on whether you prefer straightforward cashback or rewards that match your lifestyle.
Check Cashback Limits and Spending Conditions
A high cashback percentage may look attractive, but it does not always translate into higher savings.
Some cards set monthly cashback limits, minimum spending requirements, or category-specific conditions. Others may offer promotional rates only for a limited period.
Consider this example.
Suppose two cards offer cashback on eligible online purchases. One advertises a higher rate but limits the monthly reward, while another offers a lower rate with fewer restrictions.
If your monthly spending is high, the second card could provide comparable or even greater value, depending on the applicable terms.
Before applying, check:
- The cashback rate for online transactions.
- Monthly or annual cashback limits.
- Minimum spending requirements.
- Eligible merchants and transaction categories.
- Exclusions for selected purchases or payment types.
- Conditions for receiving and redeeming rewards.
Understanding these details helps you compare the benefits you are likely to receive rather than relying only on promotional headlines.
Consider the Annual Fee
A credit card's benefits should be evaluated against its cost.
Some cards charge an annual fee in exchange for rewards, travel privileges, or other features. Others offer benefits without an annual fee.
If you primarily use your card for online shopping, calculate whether the rewards you expect to earn justify the fee.
For example, if your card charges AED 500 annually but you earn only AED 300 in rewards during the year, the rewards alone would not cover the fee.
Other benefits may influence your decision, but they should be relevant to your actual needs.
If keeping costs low is your priority, explore Top Credit Cards in the UAE with No Annual Fees to understand why no-annual-fee cards may be worth considering.
Look Beyond Rewards and Check the Interest Rate
Rewards are useful only when they do not lead to unnecessary spending or borrowing costs.
Credit cards can make online purchases convenient, but carrying an unpaid balance may result in interest charges under your card agreement. These costs can reduce or outweigh the value of the rewards you earn.
For example, earning cashback on a purchase may provide limited financial benefit if the same purchase results in interest charges because you cannot repay your outstanding balance.
Before selecting a card, understand its interest rate, repayment terms, fees, and payment deadlines.
Where eligible purchases qualify for an interest-free period, make sure you understand the conditions for retaining that benefit.
The goal is to use your credit card as a payment tool while keeping your spending within an amount you can comfortably repay.
Check International Online Transaction Fees
Many UAE residents shop on international websites for clothing, electronics, travel products, and other items.
When making purchases from overseas merchants, your card may involve foreign currency conversion and international transaction fees. The final amount charged in AED may therefore differ from the price displayed on the website.
Before using your card internationally, check:
- Foreign currency transaction fees.
- The applicable exchange rate.
- Any additional charges associated with international purchases.
- Whether rewards apply to foreign currency transactions.
- Whether certain transaction categories are excluded from rewards.
A card offering attractive domestic cashback may not necessarily provide the same benefits on international purchases.
Comparing these conditions can help you avoid unexpected costs when shopping from overseas websites.
Use Credit Card Rewards Without Overspending
One common mistake is spending more simply unlocking additional rewards.
For example, purchasing unnecessary items to meet a monthly spending threshold could cost more than the cashback you receive. Discounts can also encourage impulse purchases that were never part of your budget.
A better approach is to use your card for planned expenses and evaluate the rewards against the total cost.
Set a monthly shopping budget, review your transactions regularly, and avoid making purchases solely to earn points or cashbacks.
For more practical guidance, read How to Maximise Credit Card Rewards Without Overspending in the UAE.
Remember that the most rewarding card is not necessarily the one that encourages the most spending. It is the one that provides useful benefits to purchases you would make anyway.
Compare Cards Before Planning
Once you understand your spending habits and preferred benefits, compare available credit cards before applying.
Look at the complete package rather than focusing on a single feature. Cashback rates, reward points, annual fees, minimum salary requirements, interest charges, and international transaction fees can all influence the value a card provides.
Also, check the bank's latest eligibility requirements and card terms, as offers and conditions may change.
Test My Card makes this process easier by helping users explore personalized credit card recommendations based on their profile, existing card, and eligibility.
Instead of manually comparing multiple bank websites, you can review relevant options and decide which features best match your spending needs.
Visit Test My Card to explore credit card options and make a more informed decision.
Final Thoughts
Choosing the right credit card for online shopping in the UAE requires more than comparing cashback percentages.
Your spending habits, annual fees, reward limits, interest charges, and international transaction costs all affect the value you receive.
Start by understanding where you spend, compare the benefits available, and check the conditions attached to each card. Most importantly, use your credit card responsibly and prioritize repayments over rewards.
A suitable card should complement your existing spending habits, offer benefits you can genuinely use, and help you manage payments without unnecessary financial pressure.
Explore your options with Test My Card and find a credit card that fits your needs.
Latest Post
How to Build a Strong Credit History in the UAE Using Your Credit Card
Most people in the UAE get a credit card for the rewards. The cashback, the lounge access, and the dining discounts are the obvious reasons.
Why 2026 Is the Best Time to Be a Credit Card Holder in the UAE
Credit cards in the UAE have historically been approached with a degree of caution. While the rewards on offer were often appealing, eligibility requirements, complex fee structures
Choosing the Right Credit Card for Your Family in the UAE
Family life in the UAE comes with a unique spending pattern. Unlike single professionals who may concentrate their expenses on travel, dining, or lifestyle purchases,
How Much Credit Card Cashback Can You Realistically Earn in a Year
One of the most common questions credit card users in the UAE ask is simple, but important
The Smart Traveller's Guide to Using Credit Cards Abroad
For many UAE residents, international travel is no longer a once-a-year event. Whether it is a summer escape to Europe, a family holiday in Asia, or a quick city break over a long weekend, spending abroad has become a regular part of life.
Best Credit Cards for Booking Flights and Hotels This Summer in the UAE
Summer is one of the busiest travel seasons for UAE residents. Whether you're heading to London for cooler weather, Istanbul for a long weekend, the Maldives for a family holiday, or flying home to visit relatives, chances are your biggest expenses will be flights and accommodation.
How to Maximise Credit Card Rewards Without Overspending in the UAE
Most people in the UAE approach credit card rewards the wrong way. They assume more spending means more rewards
Premium vs. Entry-Level Credit Cards in the UAE- Is the Annual Fee Worth It?
You have seen them, the sleek metal cards, the platinum tiers, the promises of lounge access and complimentary chauffeur rides
How to Maximise Your Credit Card Rewards This Eid Al-Adha
Eid Al-Adha is almost here, falling on 26th May this year, and with it comes one of the biggest spending seasons on the UAE calendar
Should You Get Multiple Credit Cards? A UAE Guide
If you've ever wondered whether having more than one credit card is a smart move or a recipe for debt
Best Credit Cards for Dining in the UAE : Earn While You Eat
Let's be honest — if your credit card isn't rewarding your Friday brunch, your weeknight takeaway, or your third coffee of the day, it's not working harder for you.
The Best Credit Cards for Grocery Shopping in the UAE
Groceries are non-negotiable. For a typical UAE household of four, monthly supermarket spending ranges from AED 2,500 to AED 4,000
How to Apply for Your First Credit Card in the UAE
Applying for a Credit Card in the UAE should be simple. Between salary thresholds, AECB score requirements, and a market that has genuinely changed in 2025,
Cashback vs. Air Miles: Which UAE Credit Card Is Right for You?
Credit cards in the UAE offer an impressive array of benefits. Two of the most popular features residents look for are cashback rewards and air miles. Each offers distinct advantages, but they work differently and suit different spending habits.
5 Common Mistakes to Avoid When Choosing a Credit Card in the UAE
Credit cards in the UAE offer a world of convenience and valuable benefits — from cashback and travel rewards to shopping discounts and exclusive services. Yet, despite countless offers and promotions, many residents end up choosing cards that don’t truly suit their needs.
How to Use Test My Card to Find the Best Credit Card for You in Minutes
The UAE has one of the most diverse credit card markets in the world. Cashback, air miles, shopping discounts, travel perks—every bank offers different deals to attract customers. While this competition benefits consumers, it also creates confusion.
Salary Below AED 5,000 in the UAE? What You Should Know About Credit Card Eligibility
In the UAE, many residents earning below AED 5,000 assume that credit cards are completely out of reach. While income requirements do play an important role, it is equally essential to understand how today’s lending rules
Top 5 Credit Cards in the UAE with No Annual Fees
For many residents in the UAE, credit cards are essential tools for everyday life — offering convenience, security, and valuable rewards. However, one feature that often frustrates users is the annual fee
How to Choose the Right Credit Card for Online Shopping in the UAE
Online shopping has become a regular part of life in the UAE. From ordering groceries and electronics to buying clothes, booking services and shopping during major sales, digital payments make everyday purchases easier.
How to Read Your Credit Card Statement in the UAE: A Simple Guide
Using a credit card is convenient, whether you are shopping online, paying for groceries, booking flights, or managing everyday expenses.
Money Lessons Should Start Before the First Paycheque
Most children encounter money long before they understand what it means. They watch their parents pay for groceries, order food, use a card at a restaurant, shop online or make payments through their phones.
The UAE Financial Vocabulary: Making Sense of the Terms You See Every Day
Walk into any UAE bank, browse a credit-card comparison page or scroll through an offer online, and you are likely to come across a familiar pattern.

The Convenience of “Buy Now”: How Delayed Payments Change the Way We Spend
You see a phone priced at AED 3,000. Then, right next to it, you see: AED 250 per month.
The Financial Domino Effect: How One Money Decision Can Change Everything Else
Money decisions rarely happen in isolation. You may think you are simply taking a new credit card, increasing your credit limit, moving to a more expensive apartment, taking a personal loan, or switching your bank.
The Spending Paradox: Why a High Salary Can Still Feel Like It's Not Enough
A higher salary should make you feel financially better off. You earn more, so naturally, you expect to have more money available for savings, investments, travel and the things you enjoy
Financial FOMO: Are You Choosing Products Because Everyone Else Is?
Your colleague just got a new credit card because the cashback is insane. Your cousin switched banks because their favourite influencer swears by it.
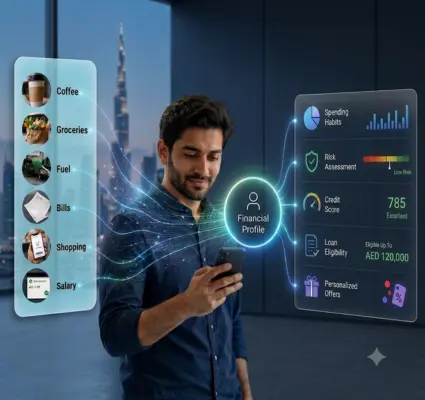
The Data Behind Your Wallet: How Banks Understand Your Financial Behaviour
Every time you tap your card at a coffee shop, pay a utility bill, or transfer money to a friend, you're leaving behind a small piece of information.
Your Money Personality: Are You a Saver, Spender, Optimiser, or Maximiser?
Ask two people with the same salary how they handle money, and you'll often get two completely different answers. One keeps a strict budget and rarely touches their savings.
The Personal Finance Reset: 5 Things Everyone Should Review Every Year
Most of us wouldn't drive a car for a full year without a service check. Yet many people go twelve months or more without giving their finances the same basic maintenance
How AI Is Changing the Way UAE Residents Choose Credit Cards
Until recently, choosing a credit card in the UAE meant scrolling through bank websites, opening a handful of tabs
Big-Ticket Purchases Made Easy: How 0% Instalment Plans Work on UAE Credit Cards
Buying a new laptop, upgrading your home appliances, or booking a family trip often means spending a large amount of money in one go. For many UAE residents
How Minimum Salary Thresholds Are Set and Why They Vary by Card Tier
Every UAE bank checks one thing first when reviewing a credit card application: your monthly salary. Before anything else is considered
The Rise of Super App Co-Branded Cards (noon, Talabat, Careem) and What They Mean for Your Rewards
UAE banks are increasingly building credit cards around the apps people already use every day, rather than offering generic cashback on broad spending categories
Understanding Interest-Free Periods : How to Enjoy Your Credit Card Without Paying a Dirham in Interest
Picture this: your salary gets credited on the 1st, and by the 25th, you've swiped your card for everything from groceries to a weekend trip.
The Psychology of Swiping: Why Credit Cards Feel Different from Cash
Picture two Fridays. On the first, you withdraw AED 500 in cash for brunch at a restaurant in Dubai Marina, and you feel every dirham leave your wallet as the bill adds up.
How to Build a Strong Credit History in the UAE Using Your Credit Card
Most people in the UAE get a credit card for the rewards. The cashback, the lounge access, and the dining discounts are the obvious reasons.
Why 2026 Is the Best Time to Be a Credit Card Holder in the UAE
Credit cards in the UAE have historically been approached with a degree of caution. While the rewards on offer were often appealing, eligibility requirements, complex fee structures
Choosing the Right Credit Card for Your Family in the UAE
Family life in the UAE comes with a unique spending pattern. Unlike single professionals who may concentrate their expenses on travel, dining, or lifestyle purchases,
How Much Credit Card Cashback Can You Realistically Earn in a Year
One of the most common questions credit card users in the UAE ask is simple, but important
The Smart Traveller's Guide to Using Credit Cards Abroad
For many UAE residents, international travel is no longer a once-a-year event. Whether it is a summer escape to Europe, a family holiday in Asia, or a quick city break over a long weekend, spending abroad has become a regular part of life.
Best Credit Cards for Booking Flights and Hotels This Summer in the UAE
Summer is one of the busiest travel seasons for UAE residents. Whether you're heading to London for cooler weather, Istanbul for a long weekend, the Maldives for a family holiday, or flying home to visit relatives, chances are your biggest expenses will be flights and accommodation.
How to Maximise Credit Card Rewards Without Overspending in the UAE
Most people in the UAE approach credit card rewards the wrong way. They assume more spending means more rewards
Premium vs. Entry-Level Credit Cards in the UAE- Is the Annual Fee Worth It?
You have seen them, the sleek metal cards, the platinum tiers, the promises of lounge access and complimentary chauffeur rides
How to Maximise Your Credit Card Rewards This Eid Al-Adha
Eid Al-Adha is almost here, falling on 26th May this year, and with it comes one of the biggest spending seasons on the UAE calendar
Should You Get Multiple Credit Cards? A UAE Guide
If you've ever wondered whether having more than one credit card is a smart move or a recipe for debt
Best Credit Cards for Dining in the UAE : Earn While You Eat
Let's be honest — if your credit card isn't rewarding your Friday brunch, your weeknight takeaway, or your third coffee of the day, it's not working harder for you.
The Best Credit Cards for Grocery Shopping in the UAE
Groceries are non-negotiable. For a typical UAE household of four, monthly supermarket spending ranges from AED 2,500 to AED 4,000
How to Apply for Your First Credit Card in the UAE
Applying for a Credit Card in the UAE should be simple. Between salary thresholds, AECB score requirements, and a market that has genuinely changed in 2025,
Cashback vs. Air Miles: Which UAE Credit Card Is Right for You?
Credit cards in the UAE offer an impressive array of benefits. Two of the most popular features residents look for are cashback rewards and air miles. Each offers distinct advantages, but they work differently and suit different spending habits.
5 Common Mistakes to Avoid When Choosing a Credit Card in the UAE
Credit cards in the UAE offer a world of convenience and valuable benefits — from cashback and travel rewards to shopping discounts and exclusive services. Yet, despite countless offers and promotions, many residents end up choosing cards that don’t truly suit their needs.
How to Use Test My Card to Find the Best Credit Card for You in Minutes
The UAE has one of the most diverse credit card markets in the world. Cashback, air miles, shopping discounts, travel perks—every bank offers different deals to attract customers. While this competition benefits consumers, it also creates confusion.
Salary Below AED 5,000 in the UAE? What You Should Know About Credit Card Eligibility
In the UAE, many residents earning below AED 5,000 assume that credit cards are completely out of reach. While income requirements do play an important role, it is equally essential to understand how today’s lending rules
Top 5 Credit Cards in the UAE with No Annual Fees
For many residents in the UAE, credit cards are essential tools for everyday life — offering convenience, security, and valuable rewards. However, one feature that often frustrates users is the annual fee
How to Choose the Right Credit Card for Online Shopping in the UAE
Online shopping has become a regular part of life in the UAE. From ordering groceries and electronics to buying clothes, booking services and shopping during major sales, digital payments make everyday purchases easier.
How to Read Your Credit Card Statement in the UAE: A Simple Guide
Using a credit card is convenient, whether you are shopping online, paying for groceries, booking flights, or managing everyday expenses.
Money Lessons Should Start Before the First Paycheque
Most children encounter money long before they understand what it means. They watch their parents pay for groceries, order food, use a card at a restaurant, shop online or make payments through their phones.
The UAE Financial Vocabulary: Making Sense of the Terms You See Every Day
Walk into any UAE bank, browse a credit-card comparison page or scroll through an offer online, and you are likely to come across a familiar pattern.
The Convenience of “Buy Now”: How Delayed Payments Change the Way We Spend
You see a phone priced at AED 3,000. Then, right next to it, you see: AED 250 per month.
The Financial Domino Effect: How One Money Decision Can Change Everything Else
Money decisions rarely happen in isolation. You may think you are simply taking a new credit card, increasing your credit limit, moving to a more expensive apartment, taking a personal loan, or switching your bank.
The Spending Paradox: Why a High Salary Can Still Feel Like It's Not Enough
A higher salary should make you feel financially better off. You earn more, so naturally, you expect to have more money available for savings, investments, travel and the things you enjoy
Financial FOMO: Are You Choosing Products Because Everyone Else Is?
Your colleague just got a new credit card because the cashback is insane. Your cousin switched banks because their favourite influencer swears by it.
The Data Behind Your Wallet: How Banks Understand Your Financial Behaviour
Every time you tap your card at a coffee shop, pay a utility bill, or transfer money to a friend, you're leaving behind a small piece of information.
Your Money Personality: Are You a Saver, Spender, Optimiser, or Maximiser?
Ask two people with the same salary how they handle money, and you'll often get two completely different answers. One keeps a strict budget and rarely touches their savings.
The Personal Finance Reset: 5 Things Everyone Should Review Every Year
Most of us wouldn't drive a car for a full year without a service check. Yet many people go twelve months or more without giving their finances the same basic maintenance
How AI Is Changing the Way UAE Residents Choose Credit Cards
Until recently, choosing a credit card in the UAE meant scrolling through bank websites, opening a handful of tabs
Big-Ticket Purchases Made Easy: How 0% Instalment Plans Work on UAE Credit Cards
Buying a new laptop, upgrading your home appliances, or booking a family trip often means spending a large amount of money in one go. For many UAE residents
How Minimum Salary Thresholds Are Set and Why They Vary by Card Tier
Every UAE bank checks one thing first when reviewing a credit card application: your monthly salary. Before anything else is considered
The Rise of Super App Co-Branded Cards (noon, Talabat, Careem) and What They Mean for Your Rewards
UAE banks are increasingly building credit cards around the apps people already use every day, rather than offering generic cashback on broad spending categories
Understanding Interest-Free Periods : How to Enjoy Your Credit Card Without Paying a Dirham in Interest
Picture this: your salary gets credited on the 1st, and by the 25th, you've swiped your card for everything from groceries to a weekend trip.
The Psychology of Swiping: Why Credit Cards Feel Different from Cash
Picture two Fridays. On the first, you withdraw AED 500 in cash for brunch at a restaurant in Dubai Marina, and you feel every dirham leave your wallet as the bill adds up.
How to Build a Strong Credit History in the UAE Using Your Credit Card
Most people in the UAE get a credit card for the rewards. The cashback, the lounge access, and the dining discounts are the obvious reasons.

