Financial FOMO: Are You Choosing Products Because Everyone Else Is?
Your colleague just got a new credit card because "the cashback is insane." Your cousin switched banks because their favourite influencer swears by it. Your group chat is buzzing about a new savings app everyone's downloading this month.
Sound familiar?
This is financial FOMO — the fear of missing out on a money move that everyone else seems to be making. And in the UAE, where the market is flooded with credit cards, savings accounts, and investment apps all competing for attention, it's easier than ever to choose a product because it's popular, not because it's right for you.
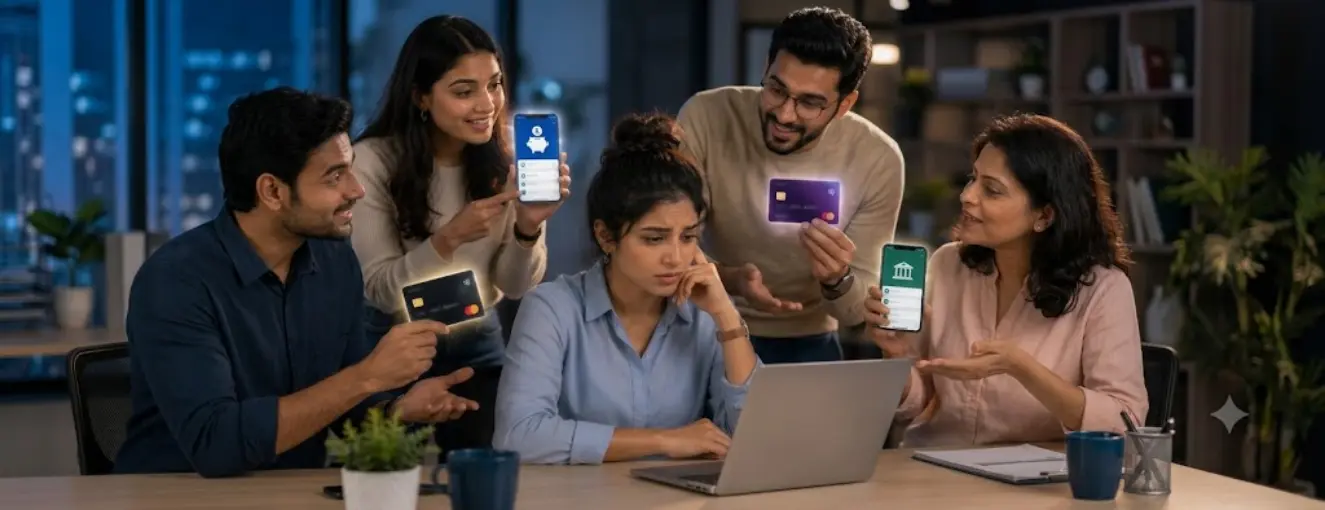
Let's break down why this happens, why it can cost you more than you think, and how to make financial decisions that fit your life.
Why Financial FOMO Feels So Real
Money decisions used to be private. Today, they're social. Between social media finance influencers, WhatsApp forwards, and friends comparing notes over coffee, personal finance has become surprisingly public — and that visibility changes behaviour.
A few reasons financial FOMO has such a strong pull:
Social proof feels like safety. If everyone around you is choosing the same credit card or savings product, it's natural to assume they've done the research, so you don't have to. This is a well-documented psychological shortcut — humans use group behaviour as a stand-in for their own due diligence, especially with decisions that feel complex or high-stakes.
Financial content is designed to trend. A card with a headline-grabbing welcome bonus or a flashy air miles reward will always get more shares and comments than a card that's simply well-suited to a specific spending pattern. The louder product wins attention, not necessarily the better-fit one.
Comparison culture never sleeps. Between salary chats, property talk, and lifestyle posts, the UAE's fast-paced, aspirational culture can make financial choices feel like status decisions rather than practical ones. Choosing "the popular card" can feel like keeping up, even when nobody's directly saying that.
None of this makes you careless with money. It makes you human. But it's worth noticing when a decision is being driven by noise rather than need.
The Real Cost of Following the Crowd
Here's the thing about trending financial products: they're often genuinely good — for the person they were designed for. The problem isn't the product. It's assuming a product built for someone else's lifestyle will serve yours just as well.
A few ways this plays out:
You pay for rewards you'll never use. A credit card famous for its airport lounge access and travel miles is fantastic if you fly monthly. If you rarely travel, you may be paying an annual fee for perks that add zero real value to your life, while missing out on a card offering cashback on the groceries and bills you spend on every month.
You miss the fine print everyone else glossed over. Popularity spreads faster than details. A card might be trending because of its sign-up bonus, but the interest rate, minimum salary requirement, or annual fee structure that kicks in after year one rarely makes it into the hype. Reviewing the eligibility criteria and full terms matters more than the headline offer.
You end up with a product that doesn't match your spending pattern. Someone who spends heavily on dining and entertainment has very different needs from someone who spends on fuel and utilities. A card optimised for one lifestyle can offer close to nothing back for another, even if it's the most talked-about card of the year.
You switch too often, chasing the next trend. Constantly moving between "the current best" product can mean missed loyalty benefits, unnecessary fees, and a credit history that looks scattered rather than stable — something that matters when banks assess your profile for bigger financial products down the line, like a mortgage or car loan.
Trend-Following vs. Needs-Based Choosing
It helps to separate the two mindsets clearly.
Trend-following starts with the question: What is everyone else using? It optimises for social validation and headline perks, and it treats popularity as a proxy for quality.
Needs-based choosing starts with a different question: What does my spending and lifestyle look like? It optimises for genuine value based on your habits, and it treats popularity as one data point among many — useful context, but not the deciding factor.
The shift from one to the other isn't about ignoring what's popular. Trending products are often popular for good reason. It's about checking whether the reason they work for the crowd also applies to you.
How to Make the Switch
Start with your own numbers, not someone else's opinion. Before comparing products, look at where your money goes. Pull up three months of spending and sort it into categories — groceries, fuel, dining, bills, travel. This tells you more about which credit card or account will serve you than any review or recommendation will.
Separate the marketing from the mechanics. A welcome bonus is a one-time event. Annual fees, reward caps, minimum spend requirements, and interest rates are ongoing realities. When you're evaluating a product, weigh the recurring terms more heavily than the one-off offer that got it trending in the first place.
Ask what "good" means for your specific goal. A card that's excellent for building a travel rewards balance may be a poor fit if your actual goal this year is paying down existing debt or building savings discipline. Define your goal first, then look for the product built around it.
Use comparison tools instead of comparison anxiety. Rather than relying on informal chatter about what's trending, use structured comparisons that lay out fees, rewards, and eligibility side by side. This turns a vague feeling of FOMO into a concrete, informed decision, based on your actual profile rather than the loudest recommendation in the room.
Give yourself a cooling-off window. If a product is trending hard, that pressure alone can be a sign to slow down rather than speed up. A few days between "I want this because everyone's talking about it" and "I've checked whether this fits me" is often enough to make a clearer decision.
The Bottom Line
There's nothing wrong with a product being popular — sometimes the crowd is onto something genuinely useful. But popularity should inform your decision, not replace your own evaluation of it. The best financial product isn't the one with the most conversation around it. It's the one that quietly, consistently works for your actual income, spending, and goals.
The next time you catch yourself considering a card or account because "everyone's getting it," pause and ask one simple question: would I still want this if no one else, had it? If the answer is yes, it might genuinely be the right fit. If you're not sure, that's usually a sign it's worth comparing your options properly before you decide.
Ready to choose based on your numbers, not the noise? Compare credit cards on Test My Card and find the one that's built for how you spend.
Latest Post
Why 2026 Is the Best Time to Be a Credit Card Holder in the UAE
Credit cards in the UAE have historically been approached with a degree of caution. While the rewards on offer were often appealing, eligibility requirements, complex fee structures
Choosing the Right Credit Card for Your Family in the UAE
Family life in the UAE comes with a unique spending pattern. Unlike single professionals who may concentrate their expenses on travel, dining, or lifestyle purchases,
How Much Credit Card Cashback Can You Realistically Earn in a Year
One of the most common questions credit card users in the UAE ask is simple, but important
The Smart Traveller's Guide to Using Credit Cards Abroad
For many UAE residents, international travel is no longer a once-a-year event. Whether it is a summer escape to Europe, a family holiday in Asia, or a quick city break over a long weekend, spending abroad has become a regular part of life.
Best Credit Cards for Booking Flights and Hotels This Summer in the UAE
Summer is one of the busiest travel seasons for UAE residents. Whether you're heading to London for cooler weather, Istanbul for a long weekend, the Maldives for a family holiday, or flying home to visit relatives, chances are your biggest expenses will be flights and accommodation.
How to Maximise Credit Card Rewards Without Overspending in the UAE
Most people in the UAE approach credit card rewards the wrong way. They assume more spending means more rewards
Premium vs. Entry-Level Credit Cards in the UAE- Is the Annual Fee Worth It?
You have seen them, the sleek metal cards, the platinum tiers, the promises of lounge access and complimentary chauffeur rides
How to Maximise Your Credit Card Rewards This Eid Al-Adha
Eid Al-Adha is almost here, falling on 26th May this year, and with it comes one of the biggest spending seasons on the UAE calendar
Should You Get Multiple Credit Cards? A UAE Guide
If you've ever wondered whether having more than one credit card is a smart move or a recipe for debt
Best Credit Cards for Dining in the UAE : Earn While You Eat
Let's be honest — if your credit card isn't rewarding your Friday brunch, your weeknight takeaway, or your third coffee of the day, it's not working harder for you.
The Best Credit Cards for Grocery Shopping in the UAE
Groceries are non-negotiable. For a typical UAE household of four, monthly supermarket spending ranges from AED 2,500 to AED 4,000
How to Apply for Your First Credit Card in the UAE
Applying for a Credit Card in the UAE should be simple. Between salary thresholds, AECB score requirements, and a market that has genuinely changed in 2025,
Cashback vs. Air Miles: Which UAE Credit Card Is Right for You?
Credit cards in the UAE offer an impressive array of benefits. Two of the most popular features residents look for are cashback rewards and air miles. Each offers distinct advantages, but they work differently and suit different spending habits.
5 Common Mistakes to Avoid When Choosing a Credit Card in the UAE
Credit cards in the UAE offer a world of convenience and valuable benefits — from cashback and travel rewards to shopping discounts and exclusive services. Yet, despite countless offers and promotions, many residents end up choosing cards that don’t truly suit their needs.
How to Use Test My Card to Find the Best Credit Card for You in Minutes
The UAE has one of the most diverse credit card markets in the world. Cashback, air miles, shopping discounts, travel perks—every bank offers different deals to attract customers. While this competition benefits consumers, it also creates confusion.
Salary Below AED 5,000 in the UAE? What You Should Know About Credit Card Eligibility
In the UAE, many residents earning below AED 5,000 assume that credit cards are completely out of reach. While income requirements do play an important role, it is equally essential to understand how today’s lending rules
Top 5 Credit Cards in the UAE with No Annual Fees
For many residents in the UAE, credit cards are essential tools for everyday life — offering convenience, security, and valuable rewards. However, one feature that often frustrates users is the annual fee
Money Lessons Should Start Before the First Paycheque
Most children encounter money long before they understand what it means. They watch their parents pay for groceries, order food, use a card at a restaurant, shop online or make payments through their phones.
The UAE Financial Vocabulary: Making Sense of the Terms You See Every Day
Walk into any UAE bank, browse a credit-card comparison page or scroll through an offer online, and you are likely to come across a familiar pattern.

The Convenience of “Buy Now”: How Delayed Payments Change the Way We Spend
You see a phone priced at AED 3,000. Then, right next to it, you see: AED 250 per month.
The Financial Domino Effect: How One Money Decision Can Change Everything Else
Money decisions rarely happen in isolation. You may think you are simply taking a new credit card, increasing your credit limit, moving to a more expensive apartment, taking a personal loan, or switching your bank.
The Spending Paradox: Why a High Salary Can Still Feel Like It's Not Enough
A higher salary should make you feel financially better off. You earn more, so naturally, you expect to have more money available for savings, investments, travel and the things you enjoy
Financial FOMO: Are You Choosing Products Because Everyone Else Is?
Your colleague just got a new credit card because the cashback is insane. Your cousin switched banks because their favourite influencer swears by it.
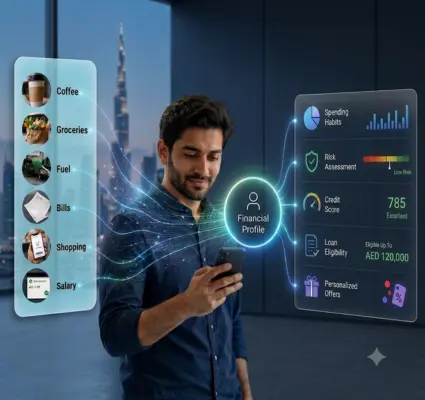
The Data Behind Your Wallet: How Banks Understand Your Financial Behaviour
Every time you tap your card at a coffee shop, pay a utility bill, or transfer money to a friend, you're leaving behind a small piece of information.
Your Money Personality: Are You a Saver, Spender, Optimiser, or Maximiser?
Ask two people with the same salary how they handle money, and you'll often get two completely different answers. One keeps a strict budget and rarely touches their savings.
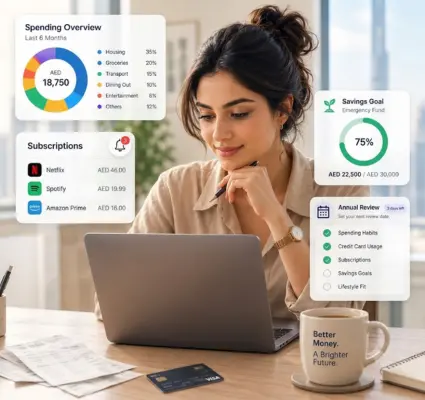
The Personal Finance Reset: 5 Things Everyone Should Review Every Year
Most of us wouldn't drive a car for a full year without a service check. Yet many people go twelve months or more without giving their finances the same basic maintenance
How AI Is Changing the Way UAE Residents Choose Credit Cards
Until recently, choosing a credit card in the UAE meant scrolling through bank websites, opening a handful of tabs
Big-Ticket Purchases Made Easy: How 0% Instalment Plans Work on UAE Credit Cards
Buying a new laptop, upgrading your home appliances, or booking a family trip often means spending a large amount of money in one go. For many UAE residents
How Minimum Salary Thresholds Are Set and Why They Vary by Card Tier
Every UAE bank checks one thing first when reviewing a credit card application: your monthly salary. Before anything else is considered
The Rise of Super App Co-Branded Cards (noon, Talabat, Careem) and What They Mean for Your Rewards
UAE banks are increasingly building credit cards around the apps people already use every day, rather than offering generic cashback on broad spending categories
Understanding Interest-Free Periods : How to Enjoy Your Credit Card Without Paying a Dirham in Interest
Picture this: your salary gets credited on the 1st, and by the 25th, you've swiped your card for everything from groceries to a weekend trip.
The Psychology of Swiping: Why Credit Cards Feel Different from Cash
Picture two Fridays. On the first, you withdraw AED 500 in cash for brunch at a restaurant in Dubai Marina, and you feel every dirham leave your wallet as the bill adds up.
How to Build a Strong Credit History in the UAE Using Your Credit Card
Most people in the UAE get a credit card for the rewards. The cashback, the lounge access, and the dining discounts are the obvious reasons.
Why 2026 Is the Best Time to Be a Credit Card Holder in the UAE
Credit cards in the UAE have historically been approached with a degree of caution. While the rewards on offer were often appealing, eligibility requirements, complex fee structures
Choosing the Right Credit Card for Your Family in the UAE
Family life in the UAE comes with a unique spending pattern. Unlike single professionals who may concentrate their expenses on travel, dining, or lifestyle purchases,
How Much Credit Card Cashback Can You Realistically Earn in a Year
One of the most common questions credit card users in the UAE ask is simple, but important
The Smart Traveller's Guide to Using Credit Cards Abroad
For many UAE residents, international travel is no longer a once-a-year event. Whether it is a summer escape to Europe, a family holiday in Asia, or a quick city break over a long weekend, spending abroad has become a regular part of life.
Best Credit Cards for Booking Flights and Hotels This Summer in the UAE
Summer is one of the busiest travel seasons for UAE residents. Whether you're heading to London for cooler weather, Istanbul for a long weekend, the Maldives for a family holiday, or flying home to visit relatives, chances are your biggest expenses will be flights and accommodation.
How to Maximise Credit Card Rewards Without Overspending in the UAE
Most people in the UAE approach credit card rewards the wrong way. They assume more spending means more rewards
Premium vs. Entry-Level Credit Cards in the UAE- Is the Annual Fee Worth It?
You have seen them, the sleek metal cards, the platinum tiers, the promises of lounge access and complimentary chauffeur rides
How to Maximise Your Credit Card Rewards This Eid Al-Adha
Eid Al-Adha is almost here, falling on 26th May this year, and with it comes one of the biggest spending seasons on the UAE calendar
Should You Get Multiple Credit Cards? A UAE Guide
If you've ever wondered whether having more than one credit card is a smart move or a recipe for debt
Best Credit Cards for Dining in the UAE : Earn While You Eat
Let's be honest — if your credit card isn't rewarding your Friday brunch, your weeknight takeaway, or your third coffee of the day, it's not working harder for you.
The Best Credit Cards for Grocery Shopping in the UAE
Groceries are non-negotiable. For a typical UAE household of four, monthly supermarket spending ranges from AED 2,500 to AED 4,000
How to Apply for Your First Credit Card in the UAE
Applying for a Credit Card in the UAE should be simple. Between salary thresholds, AECB score requirements, and a market that has genuinely changed in 2025,
Cashback vs. Air Miles: Which UAE Credit Card Is Right for You?
Credit cards in the UAE offer an impressive array of benefits. Two of the most popular features residents look for are cashback rewards and air miles. Each offers distinct advantages, but they work differently and suit different spending habits.
5 Common Mistakes to Avoid When Choosing a Credit Card in the UAE
Credit cards in the UAE offer a world of convenience and valuable benefits — from cashback and travel rewards to shopping discounts and exclusive services. Yet, despite countless offers and promotions, many residents end up choosing cards that don’t truly suit their needs.
How to Use Test My Card to Find the Best Credit Card for You in Minutes
The UAE has one of the most diverse credit card markets in the world. Cashback, air miles, shopping discounts, travel perks—every bank offers different deals to attract customers. While this competition benefits consumers, it also creates confusion.
Salary Below AED 5,000 in the UAE? What You Should Know About Credit Card Eligibility
In the UAE, many residents earning below AED 5,000 assume that credit cards are completely out of reach. While income requirements do play an important role, it is equally essential to understand how today’s lending rules
Top 5 Credit Cards in the UAE with No Annual Fees
For many residents in the UAE, credit cards are essential tools for everyday life — offering convenience, security, and valuable rewards. However, one feature that often frustrates users is the annual fee
Money Lessons Should Start Before the First Paycheque
Most children encounter money long before they understand what it means. They watch their parents pay for groceries, order food, use a card at a restaurant, shop online or make payments through their phones.
The UAE Financial Vocabulary: Making Sense of the Terms You See Every Day
Walk into any UAE bank, browse a credit-card comparison page or scroll through an offer online, and you are likely to come across a familiar pattern.
The Convenience of “Buy Now”: How Delayed Payments Change the Way We Spend
You see a phone priced at AED 3,000. Then, right next to it, you see: AED 250 per month.
The Financial Domino Effect: How One Money Decision Can Change Everything Else
Money decisions rarely happen in isolation. You may think you are simply taking a new credit card, increasing your credit limit, moving to a more expensive apartment, taking a personal loan, or switching your bank.
The Spending Paradox: Why a High Salary Can Still Feel Like It's Not Enough
A higher salary should make you feel financially better off. You earn more, so naturally, you expect to have more money available for savings, investments, travel and the things you enjoy
Financial FOMO: Are You Choosing Products Because Everyone Else Is?
Your colleague just got a new credit card because the cashback is insane. Your cousin switched banks because their favourite influencer swears by it.
The Data Behind Your Wallet: How Banks Understand Your Financial Behaviour
Every time you tap your card at a coffee shop, pay a utility bill, or transfer money to a friend, you're leaving behind a small piece of information.
Your Money Personality: Are You a Saver, Spender, Optimiser, or Maximiser?
Ask two people with the same salary how they handle money, and you'll often get two completely different answers. One keeps a strict budget and rarely touches their savings.
The Personal Finance Reset: 5 Things Everyone Should Review Every Year
Most of us wouldn't drive a car for a full year without a service check. Yet many people go twelve months or more without giving their finances the same basic maintenance
How AI Is Changing the Way UAE Residents Choose Credit Cards
Until recently, choosing a credit card in the UAE meant scrolling through bank websites, opening a handful of tabs
Big-Ticket Purchases Made Easy: How 0% Instalment Plans Work on UAE Credit Cards
Buying a new laptop, upgrading your home appliances, or booking a family trip often means spending a large amount of money in one go. For many UAE residents
How Minimum Salary Thresholds Are Set and Why They Vary by Card Tier
Every UAE bank checks one thing first when reviewing a credit card application: your monthly salary. Before anything else is considered
The Rise of Super App Co-Branded Cards (noon, Talabat, Careem) and What They Mean for Your Rewards
UAE banks are increasingly building credit cards around the apps people already use every day, rather than offering generic cashback on broad spending categories
Understanding Interest-Free Periods : How to Enjoy Your Credit Card Without Paying a Dirham in Interest
Picture this: your salary gets credited on the 1st, and by the 25th, you've swiped your card for everything from groceries to a weekend trip.
The Psychology of Swiping: Why Credit Cards Feel Different from Cash
Picture two Fridays. On the first, you withdraw AED 500 in cash for brunch at a restaurant in Dubai Marina, and you feel every dirham leave your wallet as the bill adds up.
How to Build a Strong Credit History in the UAE Using Your Credit Card
Most people in the UAE get a credit card for the rewards. The cashback, the lounge access, and the dining discounts are the obvious reasons.
Why 2026 Is the Best Time to Be a Credit Card Holder in the UAE
Credit cards in the UAE have historically been approached with a degree of caution. While the rewards on offer were often appealing, eligibility requirements, complex fee structures

